An investor’s property share does not necessarily buy your home
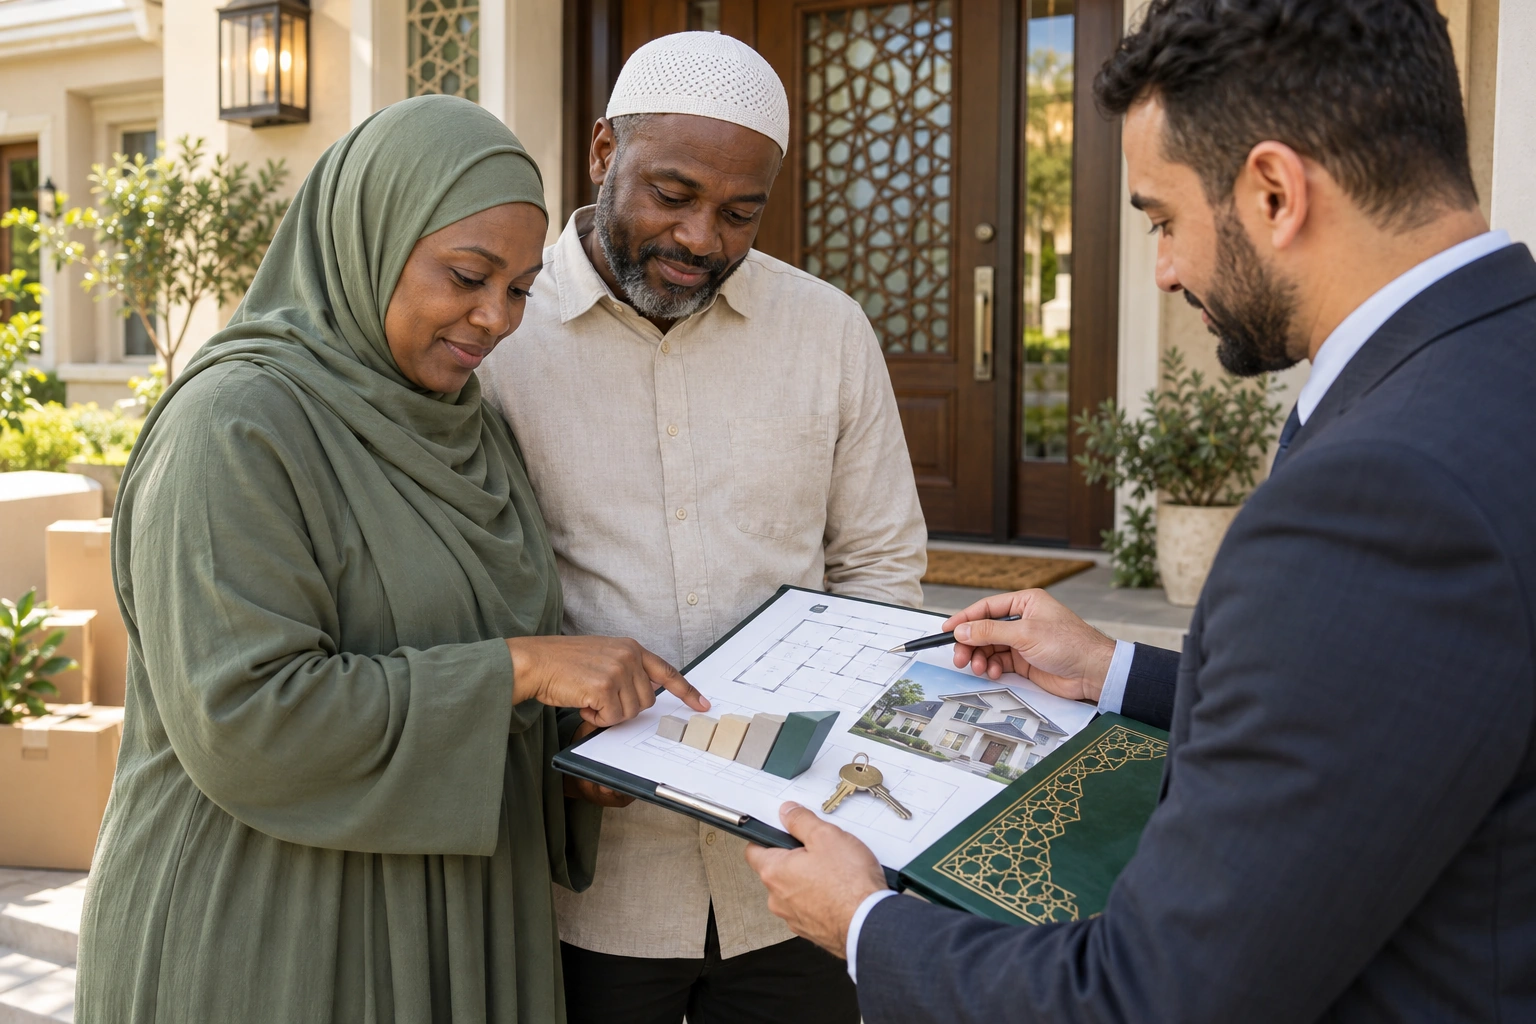
First-time buyers should distinguish three arrangements: a gift towards a deposit, financing to acquire their own home and an investment in property held for rental income. These create different legal and payment obligations. An Islamic property crowdfunding platform may serve investors without offering personal home finance at all. Before submitting an application, identify whether the proposed provider actually funds owner-occupied purchases in the buyer's jurisdiction and meets its relevant regulatory requirements.
Test affordability and ownership rights together
A homebuyer needs a clear deposit requirement, total acquisition cost and schedule showing rent or other payments alongside changes in ownership. Examine responsibility for repairs, early sale, missed payments and a fall in the property's value. Crowdfunding language should not obscure the possibility of losing the home if obligations are unmet. Compare genuine home-finance providers with investment platforms carefully, and obtain independent advice on the documents governing the property title and occupation.